Impact case
Tonnes diverted · nine material streams, weighed at the gate
Material flow mapping and supplier redesign, with every tonne weighed as it leaves the gate instead of estimated back from purchase invoices.
Diversion rates are the most over-claimed figure in corporate reporting, and the reason is structural: most of them are calculated backwards from what was bought rather than forwards from what left the site. Purchase data tells you what came in. It tells you nothing reliable about where any of it went.
This programme started by putting a weighbridge ticket behind every tonne. Nine material streams, each tracked separately, each with a named destination and a receiving facility that could be telephoned.
Thirty-one thousand tonnes diverted over the period, and the arithmetic that produces it is deliberately boring. Every figure in it traces back to a weighbridge ticket carrying a date, a destination and a vehicle, which is the only version of this number that survives somebody asking where one particular load actually went.
Loads that left without a ticket, which in the first eight months was more of them than anybody expected. Those are recorded as unevidenced rather than assumed to have been recycled. The published rate is lower than the one the site had been quoting internally, and the difference is almost exactly the unticketed volume.
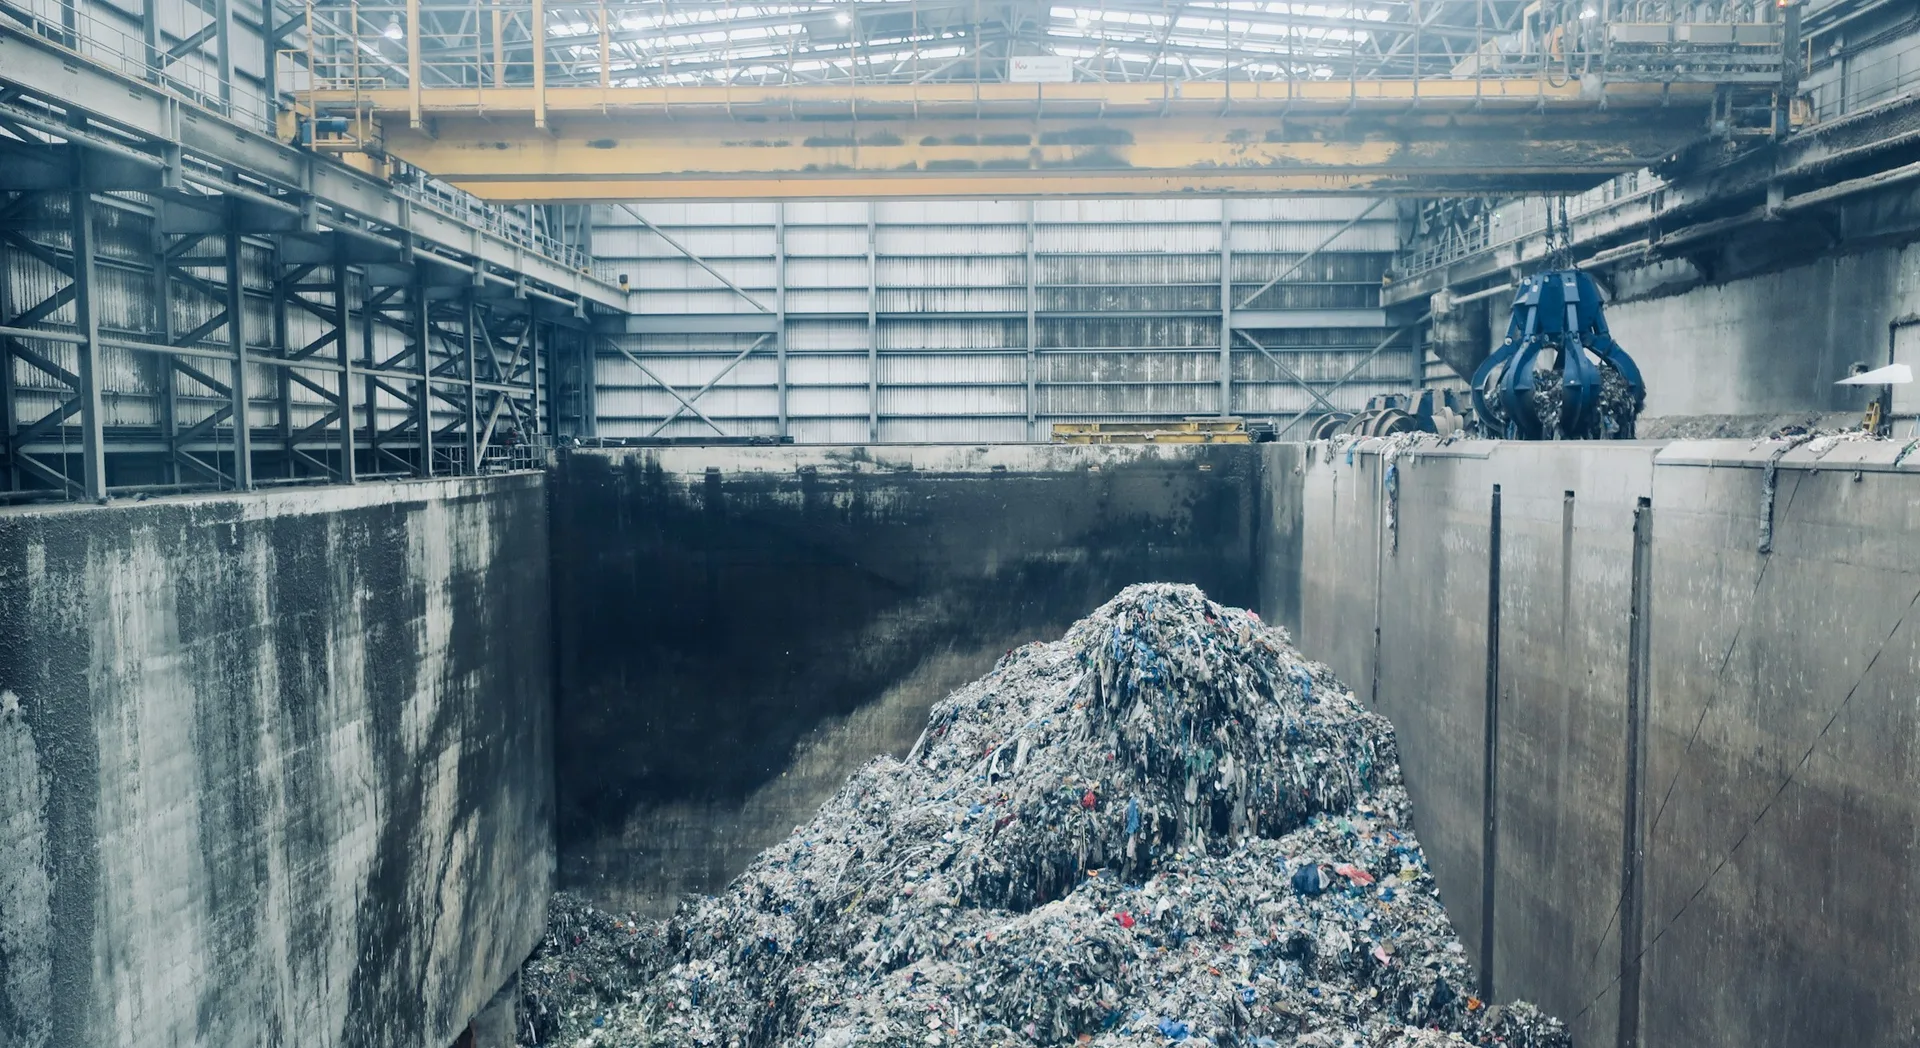
Rejected contamination has to come back out of the total. A tonne sent for recycling and then landfilled at the other end was never diverted.
The ticket archive, the stream-by-stream rates, and a supplier redesign brief covering the two packaging formats that generated most of the contamination. The brief is the part that moves next year's figure; the archive is the part that lets somebody else check this year's.
The people who signed off the figures, on what the work was like to sit through.
They opened with the three numbers in our last report they could not stand behind. It was an uncomfortable hour and it saved us a correction.
Our Scope 3 was a spend model wearing a measurement badge. They replaced the half of it that mattered and left the rest labelled as an estimate.
The disclosure draft came back with the caveats in the body rather than a footnote. Our board asked better questions because of it.